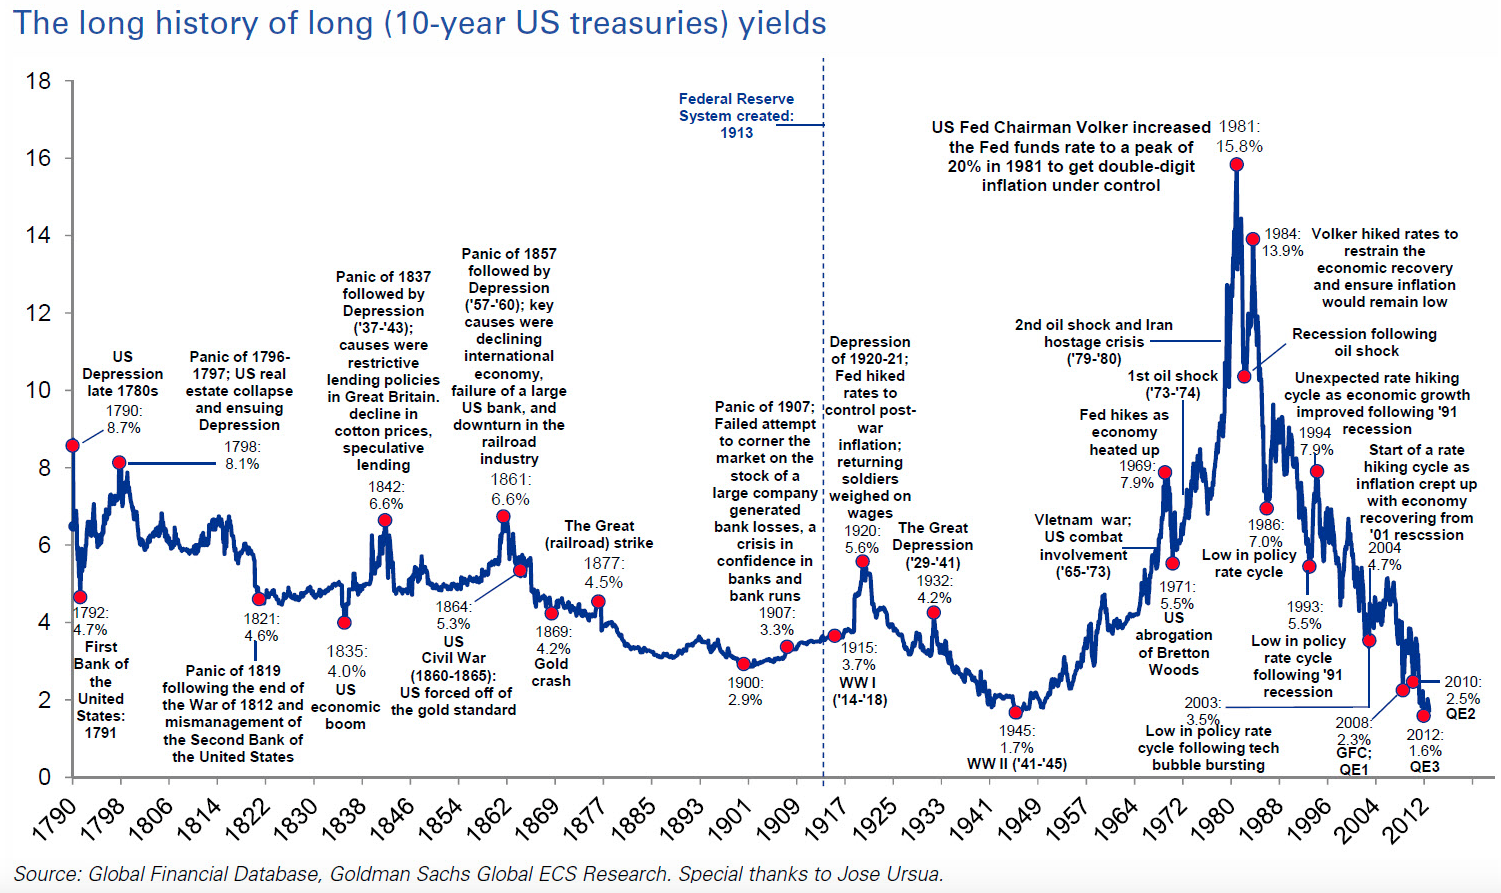
Interest rates look like tidy little percentages. Human behavior does not. Put the two together, and you get a useful laboratory for studying how people make decisions about time, risk, debt, saving, housing, and investing.
In theory, higher rates encourage saving, discourage borrowing, and reduce the present value of future cash flows. In practice, people anchor to old mortgage rates, focus on monthly payments instead of total costs, chase recent winners, and confidently forecast the Federal Reserve’s next move after reading three headlines and half a social-media thread.
That gap between textbook logic and real behavior is the territory of behavioral economics. Interest rates expose it because every rate asks the same uncomfortable question: how much is money tomorrow worth compared with money today?
Interest Rates Are the Price of Time
An interest rate is the price of borrowing money or the reward for postponing consumption. It also works as a discount rate: as rates rise, distant cash flows generally become less valuable in today’s dollars. That mechanism reaches from credit cards and mortgages to bonds, stock valuations, retirement plans, and business investment.
Suppose you can receive $1,000 today or $1,100 one year from now. The choice depends on your need for cash, expected inflation, uncertainty, and willingness to wait. Change the delayed payment to $1,300, and many people switch. Interest rates formalize that trade-off, but our preferences are not always stable or perfectly rational.
Present Bias: Future You Gets the Bill
Present bias is the tendency to give immediate rewards and costs too much weight. It helps explain why someone may understand that carrying credit card debt is expensive yet still decide that today’s purchase is a problem for next month’s version of themselves.
A 24% APR feels abstract. The new laptop, vacation, or emergency repair feels immediate. Interest arrives later, disguised inside a minimum payment. Research has linked present-biased preferences with a greater likelihood of credit card borrowing and higher balances. Other household-finance research shows that consumers may keep low-yield savings while carrying much more expensive revolving debt.
The lesson is simple: knowing a future cost is not the same as feeling it. Counter the bias by translating percentages into dollars, using automatic payments, and adding a waiting period before purchases that cannot be paid off immediately.
Money Illusion: Nominal Rates Can Fool Us
People naturally notice nominal numbers. A savings account paying 4% sounds profitable, but the real return depends on inflation, taxes, and fees. If the account earns 4% while prices rise 3%, the approximate real gain is only 1% before taxes. If it earns 2% while inflation is 4%, the balance grows in dollars while purchasing power shrinks.
This is money illusion: treating nominal values as though they were real values. Housing research has shown how buyers can misjudge affordability when comparing rent with current nominal mortgage payments without fully considering inflation and the changing real burden of fixed payments. The significance of a nominal interest rate therefore depends heavily on inflation.
Whenever you see a rate, ask whether it is nominal or real, whether inflation is included, and whether taxes, fees, or default risk reduce the return. A headline yield can be attractive while the underlying deal quietly eats your lunch.
Anchoring and the Search for a “Normal” Rate
Anchoring occurs when an initial number has too much influence on later judgments. Rate cycles produce anchors everywhere.
A homeowner who once secured a 3% mortgage may view 6% as outrageous, even when the newer rate is reasonable in a different economic environment. A saver accustomed to near-zero yields may treat a 4% deposit rate as permanently generous. An investor raised during an era of cheap money may continue valuing long-duration assets as though discount rates never change.
The anchor may be an existing loan, a friend’s quote, a central bank target, or the first offer shown by a lender. Instead of asking whether today’s rate feels high or low, compare it with current alternatives, inflation expectations, credit risk, loan terms, and after-tax returns. One number creates a story; a range creates perspective.
Loss Aversion and Mortgage Lock-In
Loss aversion means losses usually feel more painful than equivalent gains feel pleasurable. Interest rates make that tendency visible in housing and bond markets.
A homeowner with a low fixed-rate mortgage may face a sharply higher payment after moving. Staying can be financially rational, but surrendering the old rate may also feel like giving up a prized possession. Federal Reserve research estimated that mortgage-rate lock-in explained 44% of the decline in mortgage-borrower mobility from 2021 to 2022. The finding shows how a real financial cost can combine with a powerful reference point and reshape behavior across an entire market.
Bond investors face a related challenge. When rates rise, prices of existing fixed-rate bonds generally fall because new bonds offer higher yields. An investor may refuse to sell a bond showing a paper loss even when another choice better fits current goals. The purchase price becomes emotionally important, although the market has no sentimental attachment to it.
Recency Bias and Overconfident Rate Forecasts
Recency bias causes people to overweight the latest events. After years of falling rates, borrowers may assume cheap money will soon return. After a rapid hiking cycle, savers may assume attractive cash yields will last indefinitely.
This can distort portfolios. Investors may abandon long-term assets after cash yields rise, then chase stocks or long-duration bonds after rates fall and prices have already adjusted. Fidelity’s investor education materials warn that recency bias can encourage buying near market tops and selling near bottoms.
Overconfidence adds another problem. Investors make concentrated bets because rate cuts seem “obvious,” refinancing appears “certain,” or an adjustable-rate loan looks safe under one forecast. A better approach is to assign probabilities to several scenarios and ask whether the plan survives each one. Forecasting is unavoidable; pretending uncertainty does not exist is optional.
Framing and Salience: The Monthly Payment Trap
The same loan can feel affordable or expensive depending on its presentation. A lender may emphasize a manageable monthly payment while extending the repayment term. The borrower receives relief today but may overlook a larger total interest bill.
Financing $30,000 over seven years instead of five can lower the monthly payment while keeping the borrower in debt longer. Nothing magical happened. The cost simply moved out of the spotlight.
APR, APY, teaser rates, discount points, minimum payments, and compounding rules also make comparisons difficult. Research on refinancing communications suggests that translating rates into monthly payments and personalized savings can help consumers act on complex information.
Force every offer into the same frame. For a loan, compare APR, payment, total interest, fees, term, and payoff date. For savings, compare APY, restrictions, taxes, insurance coverage, and how long the advertised rate lasts.
Inertia, Mental Accounting, and the Cost of Doing Nothing
People often remain with an existing account or loan because changing requires attention. A saver may leave $25,000 in an account paying 0.5% when similar insured products pay more. A borrower may postpone refinancing even when potential savings exceed switching costs. Doing nothing feels neutral, but it still has a price.
Mental accounting creates another puzzle. A household may label one account “emergency savings” while treating a high-rate credit card as a separate problem. The labels provide emotional safety, yet they can prevent a rational comparison between a low savings yield and an expensive borrowing rate.
Behavioral-design research identifies inertia, present bias, limited attention, and choice complexity as persistent obstacles to stronger financial outcomes. A practical response is to schedule account and debt reviews once or twice a year, preserve a clearly defined emergency reserve, and direct excess cash toward the costliest debt.
Herding and Confirmation Bias
When rates move sharply, stories spread quickly. One group declares that cash is king. Another calls bonds a once-in-a-generation opportunity. A third predicts the collapse of every indebted company before lunch.
Herding encourages people to follow the crowd, while confirmation bias pushes them toward information supporting a preferred view. Social media magnifies both. FINRA specifically warns that investors using social platforms may be vulnerable to confirmation bias and peer pressure.
The antidote is to ask what evidence would prove your favorite rate story wrong. A belief that cannot be challenged is not analysis; it is merchandise.
A Behavioral Checklist for Interest-Rate Decisions
Convert Percentages Into Dollars
Calculate the annual and total dollar impact. A one-point rate difference on a large, long-term loan can matter far more than a promotional bonus.
Separate Nominal Return From Real Return
Subtract expected inflation as a rough first step, then consider taxes, fees, and risk.
Compare Total Cost, Not Only Monthly Cost
A longer term can make expensive borrowing look comfortable. Comfort matters, but it is not the same as cheapness.
Identify the Anchor
Ask whether an old mortgage, a recent market high, a friend’s quote, or a round number is shaping your judgment.
Use Scenarios Instead of One Prediction
Test the decision under higher, lower, and unchanged rates. A strong plan should remain workable when the forecast is wrong.
Automate and Add Friction
Automate saving, debt payments, and rebalancing. Add a 24-hour delay before taking variable-rate debt or making a large rate-driven portfolio shift.
Experiences Related to Interest Rates and Behavioral Biases
The clearest lessons rarely arrive in an economics lecture. They arrive when a mortgage quote, bank account, or bond statement makes someone ask, “Why am I doing this?” The following are composite experiences based on common consumer and investor behavior, not the personal financial history of the writer.
The Saver Who Celebrated the Headline
A saver moved a large emergency fund into an account advertising an attractive APY. The decision looked excellent until the promotional period ended and the rate quietly dropped. Because the original rate had become the anchor, the account continued to feel competitive. Months passed before the saver compared alternatives.
The mistake was not a failure to understand interest. It was treating a rate-sensitive decision as permanent. A calendar reminder would have been more valuable than another hour of economic commentary.
The Borrower Who Optimized One Number
At a dealership, a buyer set a maximum monthly payment. The entire discussion then revolved around hitting that number. A longer term made the vehicle fit the budget, and the buyer left relieved.
Later, the total interest cost became visible. Monthly cash flow genuinely mattered, so the choice was not absurd. However, the framing hid the trade-off. When the same offer is shown as monthly payment, total repayment, interest expense, and payoff date, the decision often changes. Whatever number leads the conversation tends to lead the mind.
The Homeowner With the “Too Good to Surrender” Mortgage
A homeowner considering a move may compare a low existing mortgage with a much higher new rate and immediately reject the idea. Staying may be sensible, but the old rate can become so emotionally valuable that it crowds out commute time, job opportunities, space needs, maintenance costs, and family priorities.
The useful exercise is to price the entire decision. What is staying worth? What nonfinancial benefits would moving provide? Could renting, downsizing, or delaying improve the trade-off? Behavioral awareness does not mean ignoring the rate. It means preventing one vivid number from becoming the whole story.
The Investor Waiting for the Obvious Rate Cut
Many investors have made a convincing rate call that the market had already priced in. They buy bonds expecting cuts, but yields rise first. They hold cash waiting for a perfect entry while risk assets advance. They finally invest when the news feels safe, only to discover that prices moved months earlier.
A correct economic forecast can still produce a poor investment result when timing, valuation, or expectations are wrong. Diversification, gradual allocation, and predetermined rebalancing are less exciting than a heroic prediction. They are also less likely to require a dramatic explanation at dinner.
The Household With Savings and Expensive Debt
One of the most revealing situations is a household that keeps a comfortable savings balance while carrying high-rate credit card debt. On a spreadsheet, using some savings to reduce the card balance appears obvious. Emotionally, the accounts have different jobs: savings means safety, while debt means obligation.
Mental accounting can support discipline, but it becomes costly when labels block a rational rate comparison. A balanced solution may preserve a defined emergency reserve and use excess cash against the highest-cost debt.
Across these experiences, interest-rate decisions are never about mathematics alone. They involve identity, security, regret, attention, and stories about the future. The numbers matter. The mind interpreting them matters just as much.
Conclusion: Rates Measure More Than Money
Interest rates reveal how strongly we prefer immediate rewards, how easily nominal numbers confuse us, how old rates become anchors, and how quickly recent conditions become forecasts of eternity.
The goal is not to eliminate bias by replacing the human brain with a calculator. The goal is to design decisions that anticipate predictable mistakes. Convert rates into dollars. Compare real returns. Use consistent frames. Challenge the anchor. Prepare for several rate paths. Automate good behavior, and remember that doing nothing is also a choice with a cost.
Editorial note: This article is for general education and does not provide individualized financial, investment, tax, or legal advice. It synthesizes research and educational material from established U.S. institutions, including the Federal Reserve, CFPB, SEC Investor.gov, NBER, the American Economic Association, the Federal Reserve Bank of St. Louis, Brookings, Chicago Booth, FINRA, Vanguard, and Fidelity.